Liverpool high street decline is not a monolithic narrative sweeping equally across every corner of Merseyside, but rather a complex, fragmented evolution of urban commerce, civic planning, and shifting consumer expectations. When examining the structural shifts altering the fabric of our city-centre retail and neighbourhood corridors, one must look beyond broad-brush national panic and instead interrogate grounded local data. From the bustling pedestrian zones surrounding Church Street to the vibrant independent micro-economies thriving in Lark Lane and Smithdown Road, the commercial heartbeat of this city is undergoing a profound renegotiation. The Liverpool Bulletin team prepared this guide for you.
Liverpool high street decline in Liverpool city-centre retail and neighbourhood corridors?
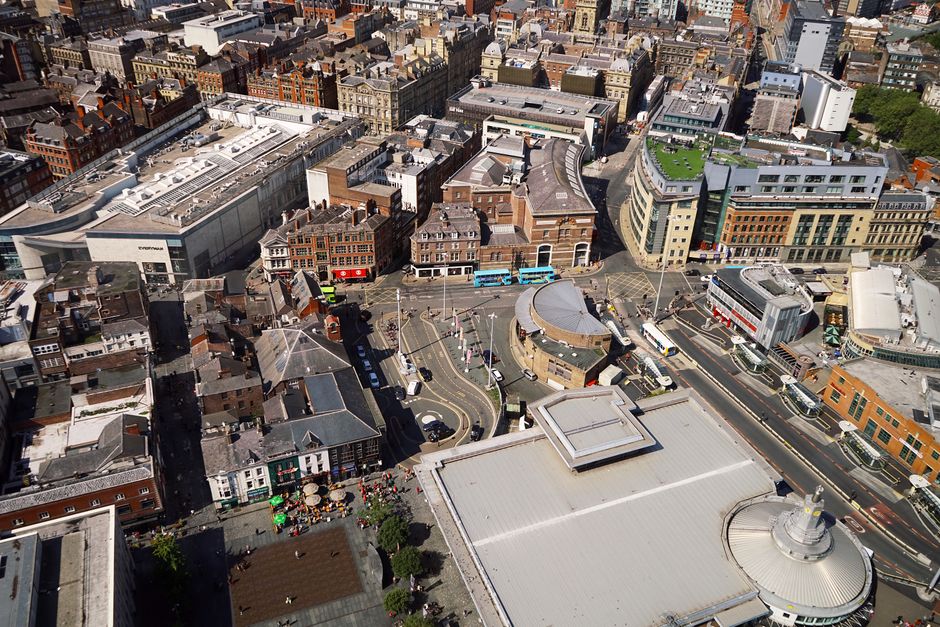
Liverpool high street decline manifests differently depending on whether one observes the corporate footprint of the city core or the resilient community-backed parades operating in outer districts. As urban centers across the United Kingdom grapple with the long-term fallout of digital commerce, remote working patterns, and soaring operational expenses, Liverpool presents a fascinating case study of adaptation, policy intervention, and structural divergence. By evaluating metrics provided by authoritative bodies such as the Office for National Statistics, Valuation Office Agency, and local civic authorities, we can construct a nuanced picture of urban transformation rather than relying on uniform generalizations.
The Origins of the Shift
Looking back at the structural transformations initiated over the past two decades, the modern urban retail environment has faced relentless economic headwinds that completely reshaped consumer habits long before recent inflationary pressures took hold. The rise of e-commerce giants fundamentally altered the traditional relationship between physical storefronts and the purchasing public, turning bricks-and-mortar retail from a default necessity into an intentional leisure choice. Within Merseyside, this macro-trend collided with localized demographic shifts, fluctuating council tax frameworks, and evolving business rate valuations overseen by agencies like the Valuation Office Agency (VOA, 2024). Consequently, commercial landlords and independent traders alike have had to reckon with spaces that no longer serve their original post-war or Victorian retail purposes.
Urban economists tracking these patterns often emphasize that metropolitan areas cannot simply wait for footfall to return to historic pre-digital peaks; instead, they must actively engineer new reasons for people to inhabit public spaces. Looking at the wider economic context documented by the Office for National Statistics (ONS, 2025), consumer spending has bifurcated sharply between experiential hospitality on one hand and essential discount retail on the other. This polarization directly impacts high streets across the Liverpool City Region, where traditional fashion chains face continuous contraction while independent food, beverage, and community-led services experience sustained demand. Navigating these economic realities requires a deep understanding of local policy frameworks, such as those governing urban aesthetics and commercial shopfront regulations across the region (see our guide on Liverpool shopfront design for more details).
Furthermore, the physical architecture of our commercial districts often reflects a bygone era of retail dominance that struggles to accommodate modern mixed-use demands. Retailers large and small must now contend with overhead costs that dwarf previous generations, forcing local governance bodies to rethink how commercial rates and urban planning permissions are administered. Engaging with these structural changes means acknowledging that high streets are fundamentally social ecosystems rather than mere transactional corridors. When a storefront remains vacant for months, it signals a deeper mismatch between landlord expectations, spatial utility, and the actual economic capacity of the surrounding neighbourhood.
Navigating the New Urban Economy
Looking ahead toward the coming decade, the revitalization of urban commerce relies heavily on diversifying neighbourhood high streets away from single-sector dependency toward resilient mixed-use models. Data compiled by the Liverpool BID Company (2025) highlights that successful urban recovery corridors are those that successfully integrate residential living, civic services, cultural spaces, and hospitality directly into the commercial mix. Rather than viewing suburban high streets as failed replicas of central shopping malls, urban planners increasingly recognize them as hyper-local community anchors that thrive on proximity, identity, and social connection.
Examining the empirical evidence provided by Liverpool City Council (2024) spatial audits reveals that districts with active evening economies and independent cultural offerings display significantly lower vacancy persistence than those reliant purely on legacy department store models. This divergence underscores why blanket declarations of retail doom fail to capture the nuanced ground reality across different Merseyside postcodes. While large corporate footprints in the retail core continue to shrink and consolidate, neighbourhood high streets frequently demonstrate remarkable agility by adapting to the immediate, everyday needs of local residents. This ongoing evolution is also deeply intertwined with broader residential dynamics, as shifts in the Liverpool property market directly influence who can live, work, and spend money within these urban communities.
To fully grasp the direction of travel for our local economy, we must consider the following key factors driving current high street transformations:
- The transition from pure retail dominance to integrated mixed-use neighbourhoods combining housing and commerce.
- The crucial role of independent hospitality and leisure in generating consistent footfall outside traditional shopping hours.
- The impact of targeted local authority interventions and BID-led initiatives on public realm improvements.
- The persistent challenge of aligning commercial property rental expectations with realistic local business revenues.
As these diverse forces continue to interact across our city region, the future of Liverpool high street decline—or conversely, its structural reinvention—will depend on collaboration between traders, landlords, and civic leadership. Understanding these dynamics ensures we move past superficial headlines to appreciate the real, gritty work of urban adaptation happening block by block. To explore more about how the wider metropolitan area is evolving through major waterfront projects, you can examine our analysis of Liverpool Waters regeneration.
Ultimately, the story of Liverpool’s commercial spaces is still being written by the people who live, work, and invest in our local communities every single day. By maintaining an analytical, data-driven approach to vacancy rates, consumer habits, and structural policy, we can better support the vibrant districts that give our city its unique character. You can contact us for any questions.
References:
Liverpool BID Company. (2025). Annual City Centre Footfall and Business Resilience Report. Liverpool: Liverpool BID Company.
Liverpool City Council. (2024). Local Authority Spatial Audit and Retail District Analysis. Liverpool: LCC Planning Division.
Office for National Statistics [ONS]. (2025). Retail Sales Index and Consumer Trends in the North West. London: ONS.
Valuation Office Agency [VOA]. (2024). Non-Domestic Rating: Commercial Property Floorspace and Rateable Values. London: VOA.